Every six months, exchange committees sit in air-conditioned boardrooms and shuffle deck chairs on the Titanic. The latest ritual sacrifice to market gravity involves tweaking index methodologies to pull in fast-growing private darlings, hoping a fresh coat of paint hides structural rot. The consensus says that if you inject enough high-beta venture darlings into a stale benchmark, the index will magically heal its performance woes.
It is a comforting fantasy for bureaucrats who refuse to look at the plumbing.
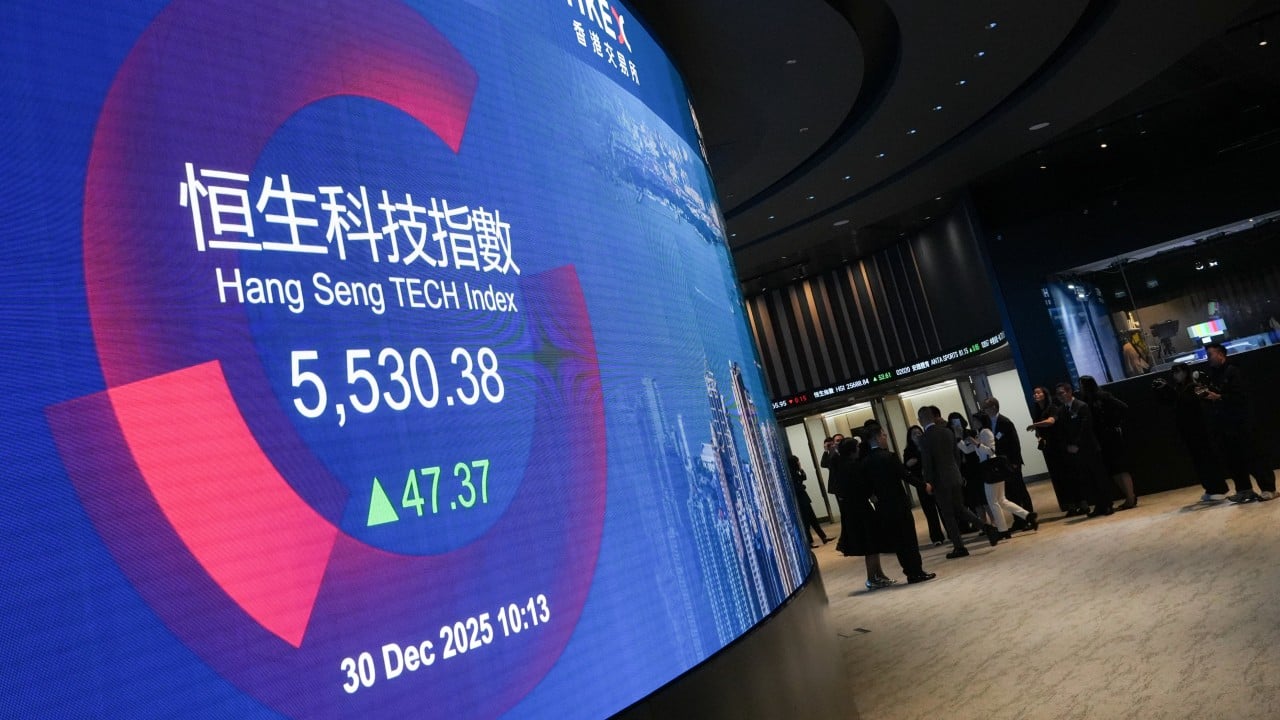
I have watched fund managers burn billions chasing index cosmetic surgeries across global exchanges, only to realize that stitching growth narratives onto a decaying foundation achieves nothing. Changing the inclusion criteria for the Hang Seng TECH Index does not fix the underlying capital allocation sickness. It just gives underperforming portfolios a shinier wrapper.
Let us dismantle the lazy consensus piece by piece.
The Growth Trap Nobody Wants To Name
The prevailing narrative treats growth like a magic wand. Add more revenue velocity, sprinkle in some artificial intelligence or cloud computing buzzwords, and watch the price-to-earnings multiples expand. But revenue velocity without pricing power or capital discipline is just an expensive way to incinerate cash.
When exchanges lower the barrier for fast-growing enterprises, they often import systemic volatility without the balance-sheet resilience required to weather a liquidity squeeze. High burn rates look phenomenal during zero-interest-rate regimes. When the cost of capital normalizes, those same high-growth darlings become anchor weights dragging down passive holders.
The index creators assume that market participants buy tickers based on growth metrics alone. Institutional capital does not work that way. Global allocators look at institutional depth, regulatory predictability, and macro liquidity flows. None of those variables improve simply because a loss-making software platform meets a new quarterly revenue threshold for inclusion.
Structural Headwinds Masked By Cosmetic Tweaks
To understand why tinkering with index weightings fails, look at what actually drives Asian capital flows today.
Liquidity in the region faces a structural squeeze. Domestic savings within mainland China search for safety rather than high-risk equity exposure amid prolonged property sector deleveraging. Meanwhile, foreign institutional investors view regional tech through a lens of geopolitical friction and unpredictable regulatory shifts.
When you build an index in an environment where regulatory overhang dictates enterprise valuations more than unit economics, inclusion criteria are irrelevant. You can weight a company at ten percent of the index, but if market makers are pricing in regulatory risk discounts, the stock will trade sideways at best.
The traditional defense claims that adding younger, nimbler companies diversifies sector concentration away from legacy platform giants. That argument ignores correlation. During a market drawdown, high-growth tech stocks correlate toward one. They dump together because global macro funds treat them as a single risk factor, not because their underlying business models share anything in common.
The Alternative Playbook
If restructuring index filters is a distraction, what should investors actually do? Stop looking at benchmarks as divine instruments of truth.
Passive indexing works in deep, efficient markets where market-cap weighting captures the broader economic output. In markets driven by structural policy shifts, passive benchmarks become museum exhibits of past momentum.
Smart capital abandons index-tracking in these environments. It targets bottom-up cash flow generation, balance sheet fortress metrics, and management teams with proven capital return discipline. If a company does not generate free cash flow within three years of public listing, its growth rate is an academic exercise.
The obsession with fixing the index stems from an institutional addiction to passive inflows. Exchanges need products to sell to retail and institutional asset managers who require benchmarking tools. As long as the product exists, marketers will tinker with the ingredients to pitch a turnaround story every autumn.
Do not buy the turnaround story. Look at the balance sheets, check the regulatory exposure, and accept that no methodology tweak can substitute for organic economic momentum.
The market does not care about your benchmark optimization committee. It cares about cash.